Canceled Debts, Foreclosures, Repossessions, and Abandonments
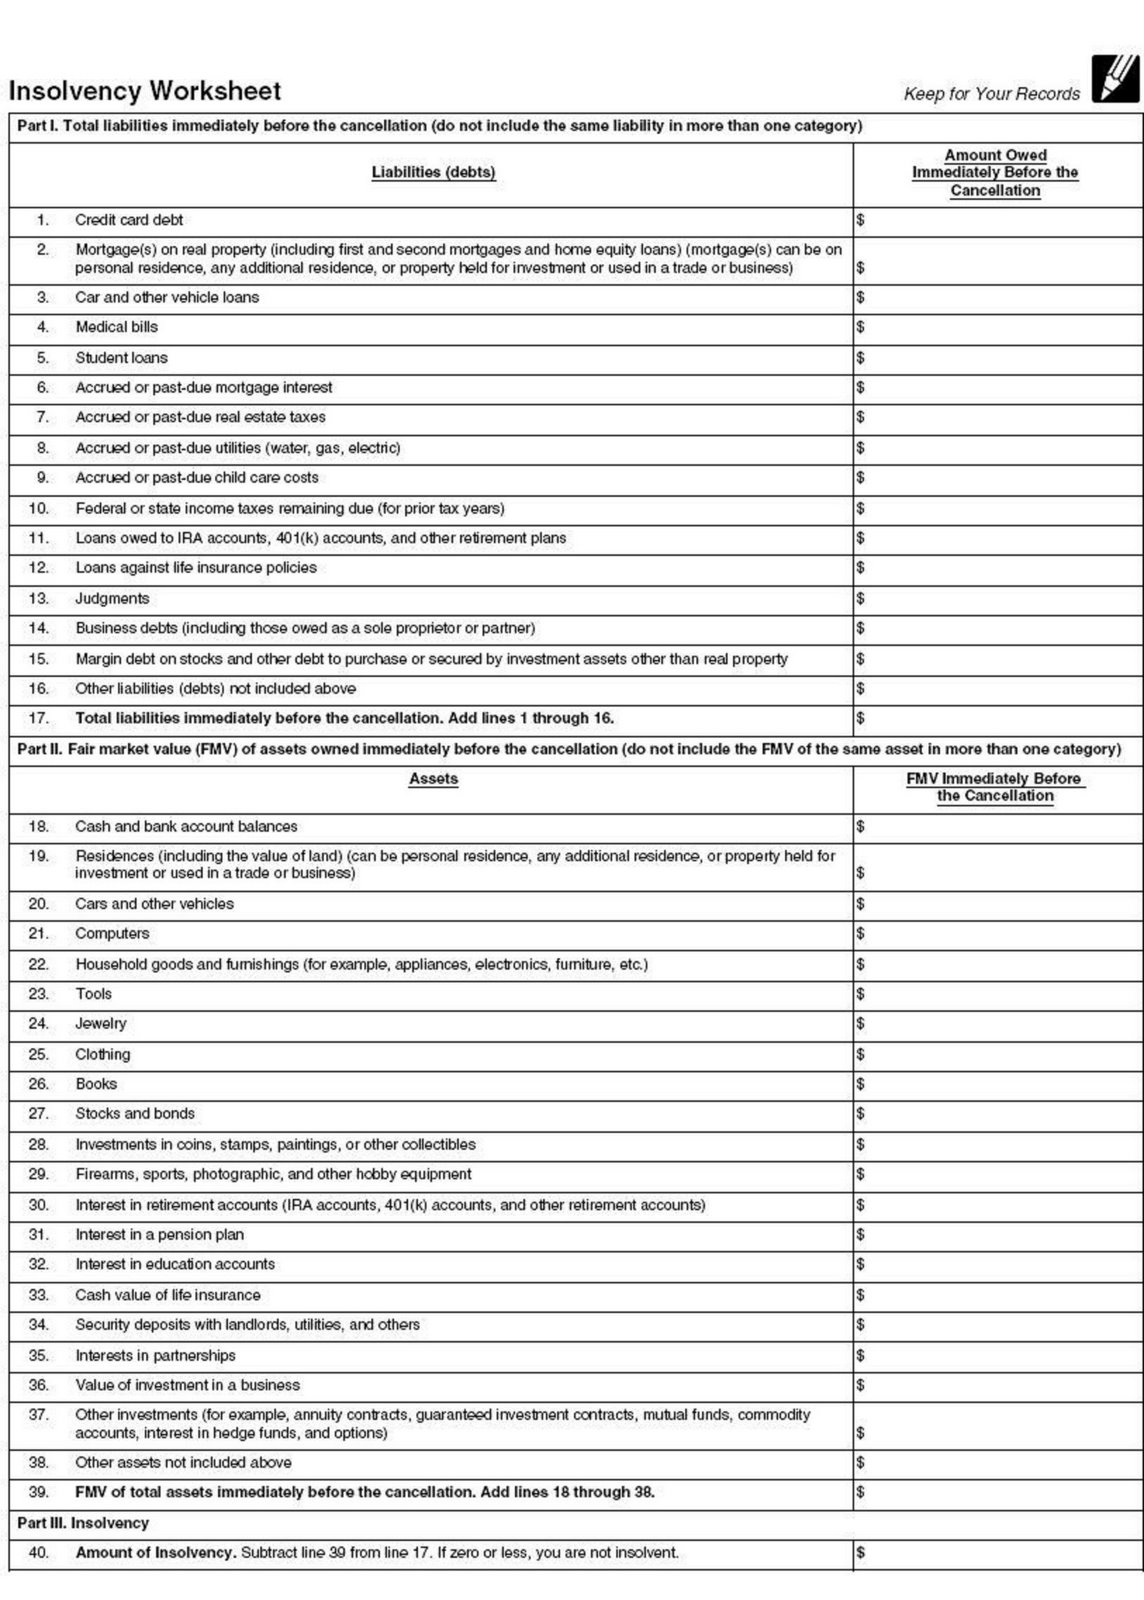
Insolvency
If you have qualified real property business indebtedness that is cancelled, you can elect to exclude this from income. However, the debt must meet the following criteria:
1) It must be incurred or assumed in connection with real property used in a trade or business.
2) It must be secured by such real property.
3) It must be incurred or assumed at either of the following times:
a. Before 1993
b. After 1992, if the debt is either (i) qualified acquisition indebtedness (defined below), or (ii) debt incurred to refinance qualified real property business debt incurred or assumed before 1993 ( but only to the extend the amount of such debt does not exceed the amount of debt being refinanced.)
4) It must be debt to which you elect to apply these rules
Qualified principal Residence indebtedness
What’s new for 2008
The qualified principle residence indebtedness exclusion has been extended. The extension includes debts discharged after 2006 and before 2013.
New Form 990
The 2008 Forms 990 and 990-EZ information returns for tax-exempt organizations are now finalized, along with schedules and instructions, for filing in 2009.
WASHINGTON –– The Internal Revenue Service released the revised instructions that tax-exempt organizations will need to fill out the redesigned Form 990, which must be filed starting with tax year 2008 (filed in 2009).
Most charities and other tax-exempt organizations must file an annual informational return with the IRS to maintain their tax-exempt status. Information reported on Form 990 is made available to the public.
“These instructions are the final step in a tremendous effort to bring the Form 990 up to date and to reflect the diversity and complexity of the tax-exempt community,” said IRS Commissioner Doug Shulman. “The revised form will give the IRS and the public a much better view of how exempt organizations operate. The improved transparency provided by these changes will also benefit the tax-exempt community.”
Form 990 had previously not seen major revisions since 1979. The revised instructions and redesigned Form 990 can be found on the IRS Web site.
The revised instructions feature several new tools that make it easier to answer questions line-by-line and that facilitate uniform reporting. Input from the tax-exempt community played a major role in how the new instructions were designed.
“We were gratified by the amount of help the IRS received from the tax-exempt community through public comments to redesign the Form 990 and revise its instructions,” said Steven T. Miller, Commissioner of the Tax Exempt and Government Entities Division. “This input helped us achieve our goal of improving compliance while minimizing burden. We will now begin working with the tax-exempt sector to help organizations complete the form and prepare for the 2009 filing season.”
The IRS expects to release instructions to the 2008 Form 990-EZ, Short Form Return of Organization Exempt from Income Tax, in the next few weeks.
As part of the phase in of the redesigned Form 990 over a three-year transition period, many organizations not eligible to file the Form 990-EZ for 2007 will be eligible to file Form 990-EZ or Form 990 for 2008. A summary of the transition period filing requirements for Form 990, 990-EZ, and 990-N is available at [link].

